Florida Business Succession Planning Attorney | Trust
By Leslie V. Marenco · Published October 20, 2026
Florida Business Succession Planning Attorney | Trust Counsel
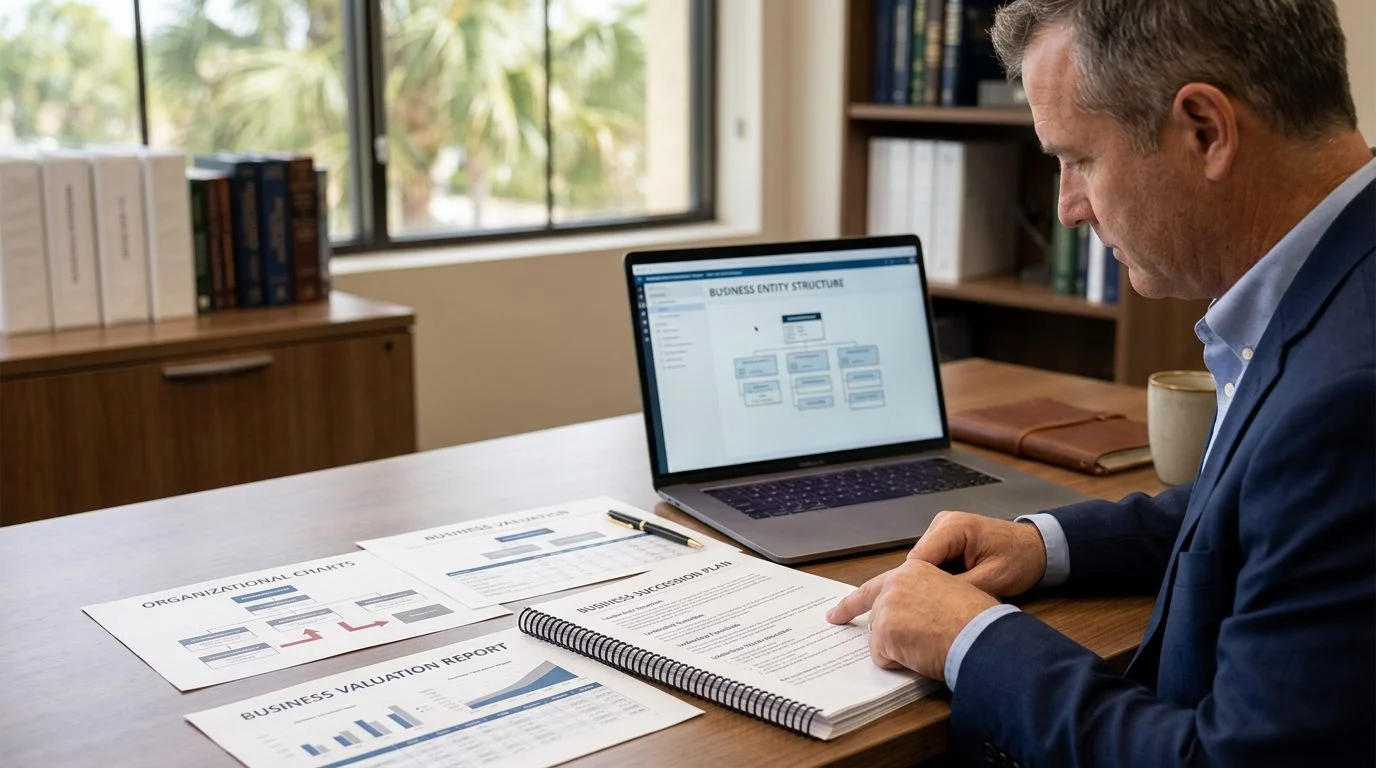
Business succession planning decides who will own, control and manage a company after its owner retires, becomes incapacitated or dies. Without that decision in writing, a family business can be left with no one clearly in charge. A business succession planning attorney Florida owners consult will look at ownership, leadership and the owner’s personal estate plan together. Trust Counsel, PL is a trusts and estates law practice in Coral Gables. This guide explains the risks, the documents and the questions that shape a plan.
Not sure what your next step is?
Talk it through with Trust Counsel, PL — the first consultation is free, confidential, and carries no obligation.
What Business Succession Planning Covers for Florida Owners
Business succession planning arranges who will own, control and run a business after the owner steps back, becomes incapacitated or dies. It answers two separate questions. The first is ownership: who holds the shares, membership units or other interest in the company. The second is leadership: who signs contracts, pays bills, hires staff and makes daily decisions.
The two questions often need different answers. A child can inherit shares in a family company without any ability to run it. A plan that handles only one question leaves a gap.
Trust Counsel focuses on trusts and estates law. That work includes business succession, estate tax planning and asset protection. Leslie V. Marenco leads this work and is the lawyer responsible for this page.
If you started your company and haven’t decided what happens to it next, that is the question to answer first. Writing the answer down turns a hope into a plan.
Risks a Closely Held Florida Business Faces Without a Plan
Without a plan, a closely held business can lose its decision-makers the day its owner dies or becomes incapacitated. Many owners assume the company will keep running on its own. Often it doesn’t.
Picture a company where the owner alone handles banking, signs the leases and approves payroll. If that owner dies, the business can stall while family members work out who has authority. Florida law provides some default rules. Under Fla. Stat. § 605.0105, an LLC’s operating agreement governs relations among members and the duties of a manager. Where that agreement is silent, the chapter’s rules apply. If an individual member dies, the member’s legal representative may exercise the member’s rights to settle the estate, under Fla. Stat. § 605.0504.
Default rules are not a plan. Co-owners who disagree, or heirs who never worked in the business, can freeze decisions. An heir who inherits shares but not control may push for distributions the managers don’t want to pay.
The specific risks depend on the company’s form, its owners and the family’s goals. Reviewing those facts is the first step in any consultation.
Core Documents in a Florida Succession Plan
A succession plan usually pairs business documents with the owner’s personal estate plan. A buy-sell agreement sets the terms for when and how an owner’s interest can be bought or transferred. ACTEC’s business owner guidance says these agreements can designate successors, address ownership and asset distribution, and plan for continuity.
Entity documents do much of the governing work. For a Florida corporation, a shareholder agreement can govern voting power, distributions and deadlock. Under Fla. Stat. § 607.0732, an agreement authorized by that section must be noted conspicuously on each share certificate or on the information statement for uncertified shares, though a failure to note it does not affect the agreement’s validity.
The owner’s personal documents must match these terms. A revocable trust is one the owner can change. Under Fla. Stat. § 736.0602, unless the trust says it is irrevocable, the settlor may revoke or amend it, but this rule does not apply to a trust created under an instrument executed before the effective date of this code. A power of attorney has limits. Under Fla. Stat. § 709.2201, an agent may only use authority the document specifically grants, and any authority reasonably necessary to give effect to that express grant of specific authority. An agent can create an inter vivos trust only if the principal signed or initialed that specific authority, under Fla. Stat. § 709.2202.
Choosing a Successor for Your Business
The right successor can both hold the ownership and run the company. Those are two separate tests, and a person can pass one and fail the other.
The usual paths are a family member, a current manager or employee, a co-owner, or a sale. A family member may bring loyalty but no operating experience. A manager may know the work but need funding to buy in. A co-owner raises buy-sell terms. A sale raises questions of timing and price. Each path needs different paperwork.
Some practical steps help. Confirm that the successor wants the role and has the ability to do it. Define the transition period, including when authority passes. Put that authority in writing, so the company knows who can act.
When a plan involves a trust or an estate, Trust Counsel’s attorneys can serve individually as trustee or personal representative (often called an executor). The firm advises and represents trustees, personal representatives and beneficiaries.
Emergency and Long-Term Succession Plans
An emergency succession plan sets out who can act for the company, and how, if the owner is suddenly unavailable. It answers practical questions. Who signs checks? Who speaks to the bank? Who approves a payroll run? Written answers keep the business moving while the family works out the larger questions.
A long-term succession plan is a phased transfer. Ownership and leadership move over the owner’s remaining working years, often in steps. The owner may hand over day-to-day control first and keep an ownership share for a set time. The steps should match the buy-sell terms and the owner’s estate plan.
Most owners need both tiers. The emergency plan covers the gap, and the long-term plan covers the path.
Have questions about what happened?
Ask Trust Counsel, PL directly. The first conversation is free, confidential, and there is no obligation to continue.
Estate Tax and Asset Protection in Business Transfers
Estate tax planning and asset protection both depend on how a business interest is held and passed. Under IRC § 2031, the gross estate includes the value at death of all property, wherever it is located.
As the IRS explains, recent federal legislation amends § 2010(c)(3) by increasing the basic exclusion amount to $15,000,000 for calendar year 2026.
Federal law also allows installments in some cases. Under IRC § 6166, if the decedent was a citizen or resident of the United States at death and an interest in a closely held business exceeds 35 percent of the adjusted gross estate, the executor may elect to pay part or all of the tax in 2 or more (but not more than 10) equal installments.
Moving a business into a trust does not always remove it from the estate. Under IRC § 2038, property can still be counted if the owner could alter, amend, revoke or terminate the transfer at death. IRC § 2038 reads: “To the extent of any interest therein of which the decedent has at any time made a transfer (except in case of a bona fide sale for an adequate and full consideration in money or money’s worth), by trust or otherwise, where the enjoyment thereof was subject at the date of his death to any change through the exercise of a power (in whatever capacity exercisable) by the decedent alone or by the decedent in conjunction with any other person (without regard to when or from what source the decedent acquired such power), to alter, amend, revoke, or terminate, or where any such power is relinquished during the 3 year period ending on the date of the decedent’s death.”
Asset protection looks at how ownership is structured and what heirs receive. The planning approach turns on the owner’s facts. The practice reviews those facts with the owner before recommending any structure.
Florida Owners With Family and Assets Across Borders
Owners with heirs or business interests outside Florida or the United States face extra questions about ownership, control and transfer. Some of those questions turn on where a document was signed. Under Fla. Stat. § 732.701, an agreement to make a will, to give a devise, not to revoke a will or devise, or not to make one is binding or enforceable only if it is in writing and signed by the agreeing party in the presence of two attesting witnesses. An agreement of this kind executed by a nonresident of Florida is valid in this state if it was valid when executed under the laws of the state or country where it was executed, whether or not the agreeing party is a Florida resident at the time of death.
Gifts also follow different rules when a spouse is not a U.S. citizen.
Trust Counsel’s work includes planning for domestic and foreign families, along with estate tax, asset protection and business succession. If a matter falls outside this practice, it may be referred to another lawyer or firm. That will be explained at the start.
Working With Trust Counsel, PL in Coral Gables
Trust Counsel, PL’s only office is in Coral Gables, Florida. Leslie V. Marenco is the lawyer responsible for this page. The practice has assistants and office staff to help with scheduling and paperwork.
We serve clients in Fort Lauderdale, Boca Raton, West Palm Beach, Doral, Kendall, Pinecrest, Key Biscayne and Aventura.
The process starts with a conversation about who owns the business, who runs it and what the owner wants. Next comes a review of the company’s documents and the family’s plans. Then the lawyer proposes a written plan. The first consultation is free, confidential and carries no obligation to continue.
Can a power of attorney run my business if I become incapacitated?
An agent’s authority is generally limited to the authority the document specifically grants, plus authority reasonably necessary to give effect to that express grant, except as provided in this section or other applicable law (Fla. Stat. § 709.2201(1)).
Can estate tax on a business be paid in installments?
Federal law lets the executor of a decedent who was a citizen or resident of the United States at death elect to pay part or all of the estate tax in 2 or more (but not more than 10) equal installments when a closely held business interest included in the gross estate exceeds 35 percent of the adjusted gross estate (IRC § 6166).
If you’re deciding who will own and run your company after you step back, call (305) 707-7126 or schedule online at https://trustcounsel.com/contact/.