Business Succession Planning | Coral Gables, Florida
Plan the Future of Your Business Before You Need To
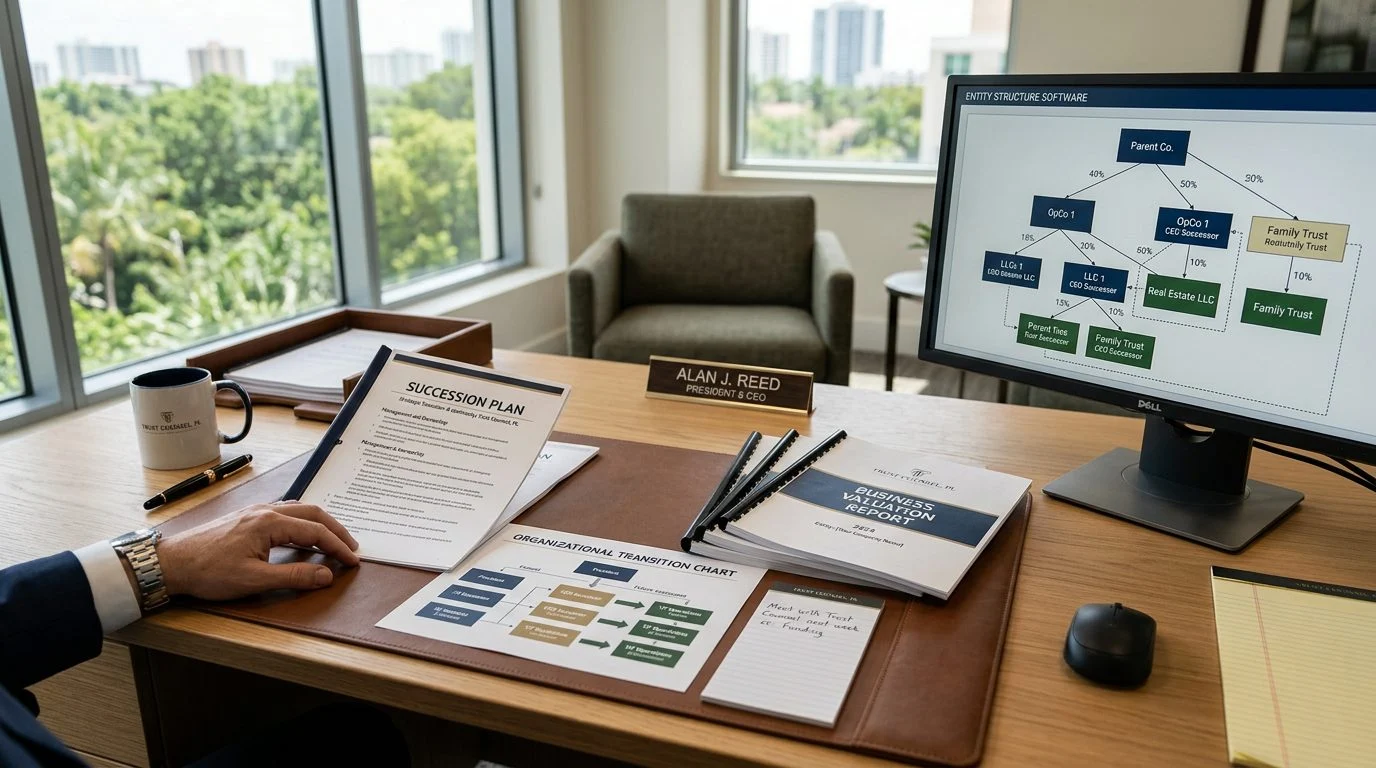
Trust Counsel, PL focuses on business succession planning for owners and families in Coral Gables and throughout South Florida, covering ownership transfer, buy-sell agreements and continuity of management.
By Leslie V. Marenco · Published October 19, 2026
Business Succession Planning Attorney Fort Lauderdale
If you have decided who should take over your company, you don't have to map out the buy-sell terms and your personal plan alone; book your first consultation with us. Talk it through with Trust Counsel, PL — the first consultation is free, confidential, and carries no obligation.
Why Fort Lauderdale Business Owners Plan Ownership Transfer Now
A business succession plan decides who will own and run your company when you step back, become unable to act, or die. Without one, those answers may come from default rules and old papers instead of your choices.
For many owners in Fort Lauderdale and Broward County, the company is a family business, a professional practice, or a closely held company with a few co-owners. Each one needs a clear written plan. Business succession planning means moving a company’s ownership, management and value to the next owners. It covers retirement, disability, death, a sale to a partner, or a transfer to children or key employees.
The plan reaches past the company’s own papers. Your will, trust and power of attorney decide what happens to your ownership interest and who acts for you. If those documents don’t match the operating agreement or shareholder agreement, the results can conflict.
Trust Counsel, PL focuses its practice on trusts, estates and business succession. The firm’s only office is in Coral Gables. We serve clients in Fort Lauderdale. Leslie V. Marenco is the lawyer responsible for this page, and office staff support the practice.
What a Business Succession Plan Covers
A complete plan answers four questions: who gets ownership, who runs the company, which documents support the change, and what the business is worth. Each question needs a decision in writing.
Ownership. The plan names who receives ownership interests, whether a child, a co-owner or an outside buyer. It also sets the timing. Some transfers happen during life. Others take effect at death.
Management. Ownership and management are different things. A transfer of an LLC interest is permissible, but the transferee does not gain the right to take part in managing the company. The plan must name who will manage, or the gap can stall the business.
Governing documents. For an LLC, the operating agreement governs relations among the members and with the company. For an LLC, the operating agreement governs relations among the members and with the company. Where the agreement does not provide for a matter it governs, such as relations among members or the company’s activities, the statute fills the gap (Fla. Stat. § 605.0105). For a corporation, a shareholder agreement that meets the statute can set who serves as director or officer and how they are chosen or removed (Fla. Stat. § 607.0732). Keep these documents aligned with your personal plan.
Value. For estate tax purposes, a deceased owner’s business interest is valued at what a willing buyer would pay a willing seller. For a deceased owner’s interest in a partnership or proprietorship, the value is determined on the basis of all relevant factors, including a fair appraisal of all business assets, tangible and intangible, including goodwill, the business’s demonstrated earning capacity, and other applicable factors (26 C.F.R. § 20.2031-3). Gather that information before you set a transfer in motion.
Buy-Sell Agreements and Funding Ownership Interests
A buy-sell agreement sets the events that trigger a buyout and the price or formula for it. ACTEC’s business owner guidance says succession plans and buy-sell agreements help owners designate successors and address ownership and asset distribution.
Triggering events usually include death, disability, retirement, divorce, or an owner who leaves the company. Each one needs a clear definition. A word like “disability” that no one defined can start a dispute at the worst possible moment.
A buy-sell agreement helps co-owners keep control inside a defined group. Without one, a departing owner’s heirs or a former spouse could end up holding an interest in the company. The agreement can also say who gets the first chance to buy.
Price is where many plans fail. A formula set years ago can produce a number far from today’s value. Review the price method on a regular schedule and tie it to current business values.
The agreement must also match the operating agreement or shareholder agreement. A conflict can leave the company’s rules and the buy-sell terms pointing in different directions. Funding answers how the buyout gets paid. Owners may use savings, installment terms or insurance. The agreement should state the payment method, so the buyout doesn’t depend on guesswork.
Trusts, Estate Tax Planning and Asset Protection for Business Interests
A trust can hold a business interest, but a trust the owner can still revoke generally leaves that interest in the owner’s taxable estate. Planning starts with how the trust is set up and what powers the owner keeps.
Florida law allows a trust to be created by transferring property to a trustee during the owner’s life, or by will or another disposition that takes effect at death, or by the owner’s declaration that the owner holds identifiable property as trustee, or by exercise of a power of appointment in favor of a trustee (Fla. Stat. § 736.0401). Under IRC § 2038(a)(1), the gross estate includes, to the extent of any interest the decedent transferred by trust or otherwise (except in a bona fide sale for an adequate and full consideration in money or money’s worth), property whose enjoyment at death is subject to a power to alter, amend, revoke or terminate it, whether held by the decedent alone or with another person, or relinquished within 3 years before death.
A business interest can raise an estate’s value, so the valuation work matters.
Some estates have a special option for business interests. If the value of an interest in a closely held business included in the gross estate exceeds 35 percent of the adjusted gross estate of a decedent who was a citizen or resident of the United States at the date of death, the personal representative (often called an executor) may elect to pay part or all of the estate tax in 2 or more (but not exceeding 10) equal installments (IRC § 6166).
Asset protection ideas for owners work alongside the operating agreement and the owner’s trust. Each idea has limits that depend on the facts. Keep the will, trust and beneficiary designations matched to the business documents.
Continuity When an Owner Becomes Incapacitated or Dies
When an owner can’t act, the plan decides who signs, votes and manages the company. Without that plan, the family may need a court process to get someone in charge.
A durable power of attorney is the main tool for incapacity. Under Fla. Stat. § 709.2104, a power of attorney is durable if it contains the required words or similar words showing the principal intends it to stay in effect after incapacity. The Florida Department of Elder Affairs explains that a durable power of attorney can avoid the appointment of a guardian. Guardianship is a court-created delegation of rights.
The LLC rules add a second layer. An individual member is dissociated when the individual dies. In a member-managed LLC, dissociation also occurs when a guardian or general conservator is appointed for the member.
After death, the personal representative handles the estate, including business interests. Trust Counsel’s attorneys can serve individually as trustee or personal representative. The firm advises and represents trustees, personal representatives and beneficiaries. Whether a business interest passes through probate or a trust changes the court steps and the timing, depending on the facts.
Planning after a health crisis is harder. The owner may no longer be able to sign new documents. Planning early keeps the choices in the owner’s hands.
Not sure what your next step is?
Talk it through with Trust Counsel, PL — the first consultation is free, confidential, and carries no obligation.
Frequently Asked Questions About Business Succession Planning in Florida
Here are short answers to four common questions about business succession planning in Florida.
Do I need a business succession plan if I have a will?
A will alone may not cover company ownership, management or buyout terms.
Can a buy-sell agreement be changed later?
It depends on the agreement’s terms. For a corporation’s shareholder agreement, Fla. Stat. § 607.0732 says changes generally need all shareholders at that time, unless the agreement provides otherwise.
Does a family member have to take over the business?
The owner chooses the successor, and the plan puts that choice in writing. The plan should also say what happens if the chosen successor cannot take over.
What should I bring to a first meeting?
Bring your company’s operating or shareholder agreement, your current will, trust and powers of attorney, and a list of owners and key employees. Having these ready helps the first meeting focus on your goals.
Talk With Leslie V. Marenco About Your Fort Lauderdale Business
If you have decided how ownership should pass in your company, Leslie V. Marenco can help you set the first documents in place. Owners reach this point for different reasons: a partner ready to retire, a parent who wants to step back, or a health event that makes the plan urgent.
The first consultation is free, confidential, and carries no obligation to continue. Call (305) 707-7126 or schedule online to book your strategy call. Trust Counsel, PL’s only office is in Coral Gables, and we serve clients in Fort Lauderdale.
Why Business Owners Plan Ahead With Trust Counsel
Coordinated planning
A business succession plan works alongside your will, trust and estate tax planning so ownership passes according to your wishes.
Continuity for your team
Clear management and ownership terms help your business keep operating when a founder, partner or shareholder steps away.
Protection for your family
Thoughtful buy-sell terms and transfer provisions can help reduce disputes among owners, heirs and fiduciaries.
Serving South Florida
We serve clients in Fort Lauderdale, Boca Raton, West Palm Beach, Doral, Kendall, Pinecrest, Key Biscayne and Aventura from our Coral Gables office.
Do not assume a will covers your company
Reviewing your governing documents and any shareholder or partnership agreement early gives you more options.
Common Business Succession Planning Topics
Buy-sell agreements
Set out how ownership interests are valued, offered and transferred when an owner retires, becomes incapacitated or passes away.
Ownership transfer
Plan how shares or membership interests move to family members, co-owners or a successor, and how those transfers fit your estate plan.
Management continuity
Identify who will lead the business and document the authority that person needs to keep operations running.
Estate tax and asset protection coordination
Align business succession decisions with estate tax planning and asset protection goals for owners and high-net-worth families.